Tag Archive for: appraisals

Relocation Appraisals for CAF & RCMP Members

Relocation Appraisals for CAF & RCMP Members in Victoria BC

A Guide to Sirva-Managed Relocation Appraisals Across Vancouver Island

Receiving a new posting brings many responsibilities, from preparing your current home for sale and organizing the move to finding a new home and helping your family transition. Amidst all these tasks, arranging a home appraisal is a vital step, especially if your relocation is managed by Sirva (formerly BGRS). For Canadian Armed Forces (CAF) personnel and RCMP officers under their federal relocation programs, often referred to as the Integrated Relocation Program (IRP), this appraisal determines the Fair Market Value (FMV) of your primary residence, which directly impacts your eligibility for various relocation benefits.

Fritz Appraisals provides relocation appraisals for CAF and RCMP members across Vancouver Island, from Victoria to Nanaimo.

Key Takeaways

  • Fair Market Value (FMV) – Your relocation appraisal establishes the FMV of your home, which determines your eligibility for CAF and RCMP relocation benefits.
  • AIC-Credentialed Appraisers – All appraisals are completed by members in good standing with the Appraisal Institute of Canada (AIC).
  • Vancouver Island Coverage – D. Fritz Appraisals serves CAF and RCMP families relocating across Vancouver Island, from Victoria to Nanaimo and the Gulf Islands.
  • Different Billing For CAF And RCMP – CAF members typically have appraisal fees billed directly to Sirva, while RCMP members generally pay upfront and file for reimbursement.
  • Personal Experience – Our team includes an RCMP family member and a CAF spouse, so we understand the relocation process firsthand.

The Role of a Professional Appraisal

An appraisal does more than just estimate a potential sale price; it delivers an objective, independent valuation based on recent market trends, local sales, and your property’s specific traits. This ensures your relocation benefits are calculated using a reliable and well-supported figure.

The appraised value can be critical for establishing:

  • Home Equity Assistance under your relocation program’s guidelines
  • Specific relocation incentives
  • Reimbursement for qualifying selling costs
  • Key decisions throughout your relocation file

Understanding the Appraisal Process

When managing your relocation, you select and schedule with your chosen appraisal provider. As an approved vendor, D. Fritz Appraisals serves clients across Vancouver Island at Sirva’s pre-negotiated rate, ensuring a fair and consistent fee for every appraisal.

For CAF Members: We handle the paperwork by sending the completed appraisal report and invoice directly to Sirva. Eligible primary residence appraisal fees are directly billed and covered through the program, subject to approval.

For RCMP Officers: Members pay for the appraisal at the time of service and apply for reimbursement through their relocation benefits.

Appraisals for rental properties, future purchases, or non-primary residences might not be covered, depending on your approved benefits. We recommend contacting Sirva to verify your coverage before booking. Once complete, we will share a copy of the report with you and directly submit the required documents to Sirva for CAF files.

CAF members can review their entitlements in the full Canadian Armed Forces relocation directive, and RCMP members can find complete details in the RCMP Relocation Directive.

While relocation files have unique program requirements, preparing for them is no different than any other appraisal. A few proactive measures, such as reviewing the inspection checklist or compiling a list of recent property upgrades, can help guarantee a smooth process. For more details, explore our complete guide: Pre-Appraisal Checklist for Homeowners.

You can also browse our full range of appraisal services for Vancouver Island homeowners.

Key Valuation Factors

Every property and local real estate market is distinct. To deliver an accurate, impartial valuation that meets relocation program standards, we analyze:

  • Location and neighbourhood dynamics
  • The home’s overall condition and quality
  • Recent upgrades, renovations, and improvements
  • Size, functional layout, and overall utility
  • Comparable recent sales data
  • Market trends and conditions
  • Local buyer demand

A Dedicated Team with Personal Experience

Our experience extends beyond professional appraisal services; we also understand the experience on a personal level.

Company owner, Bo Lott, grew up in an RCMP family and experienced the challenges of frequent moves firsthand, from switching schools to leaving friends. He brings this understanding to D. Fritz Appraisals, personally reviewing each relocation report to ensure it meets our strict quality standards.

Our Office Manager, Chelsea, is currently navigating military life as the spouse of an active Canadian Armed Forces member. Having experienced multiple moves, she is deeply familiar with the scheduling, timelines, and paperwork involved in relocations, managing coordination and administration to keep files moving seamlessly.

Our team’s background shapes how we operate. When Chelsea’s family relocated outside of British Columbia, we transitioned to a flexible remote work model that allowed her to continue supporting our clients from wherever military life takes her family. It is one more way we put people first, whether that means supporting our own team or the military, RCMP, and government families we are proud to serve every day.

Learn more from an AIC Designated Appraiser

An appraisal is just one step in your relocation journey, but it is an essential one. D. Fritz Appraisals is honoured to assist Canadian Armed Forces members, RCMP officers, and government personnel across Southern and Central Vancouver Island. Whether it is your first move or your last, you can count on our team for responsive communication, honest guidance, and firsthand expertise in the relocation process because we have lived it ourselves.

If you are preparing for a CAF or RCMP relocation appraisal anywhere from Victoria to the Comox Valley, the team at D. Fritz Appraisals is ready to help. Call us at 250-413-7319 or visit our contact page to book your appraisal today.

Why Vancouver Island Mortgage Brokers Rely on AIC-Designated Appraisers for Lender Submissions

Why Vancouver Island Mortgage Brokers Rely on AIC-Designated Appraisers for Lender Submissions

A Practical Guide for Brokers Placing Mortgages Across Southern and Central Vancouver Island

Vancouver Island mortgage brokers depend on accurate, lender-accepted property valuations to close files on time. When a lender orders an appraisal as part of a mortgage submission, the report needs to be credible, compliant, and defensible. That is why brokers placing residential mortgage financing appraisals across Southern and Central Vancouver Island consistently turn to appraisers who hold a designation from the Appraisal Institute of Canada (AIC).

This post explains what AIC designation means, why it matters to lenders, and what brokers working across Victoria, Nanaimo, the Cowichan Valley, Parksville, and the Comox Valley should look for in an appraisal partner.

Key Takeaways

  • AIC designation matters to lenders – Major Canadian banks, credit unions, and mortgage insurers require appraisal reports completed by AIC members in compliance with CUSPAP, the Canadian Uniform Standards of Professional Appraisal Practice.
  • CRA vs. AACI – The CRA designation covers residential properties with up to four units. The AACI designation authorizes an appraiser to work on any property type. Both are recognized for standard residential mortgage files.
  • Local market knowledge is non-negotiable – An appraiser who understands property values in Oak Bay, Cobble Hill, Salt Spring Island, and Parksville produces reports that hold up under lender scrutiny.
  • Fast turnaround protects your file – Mortgage files move on tight timelines. A firm that delivers accurate valuations promptly helps brokers avoid unnecessary delays and keeps clients on track.
  • Unbiased, impartial reporting – Lenders and mortgage insurers require an independent third-party opinion of fair market value. AIC members are bound by professional standards that ensure their reports are objective and legally defensible.

What AIC Designation Means for Lender Submissions on Vancouver Island

The Appraisal Institute of Canada grants two professional designations: the CRA (Canadian Residential Appraiser) and the AACI (Accredited Appraiser Canadian Institute). For residential mortgage files, the CRA designation applies to properties with up to four self-contained family housing units. The AACI designation covers the full range of property types, including commercial and multi-family buildings.

What both designations share is a rigorous path: a university degree, a structured educational program, supervised applied experience, work-product reviews, and comprehensive examinations. Members are also required to carry professional liability insurance and to adhere to CUSPAP, the mandatory standard governing how every AIC appraisal is developed and reported.

Major Canadian lenders, including chartered banks, credit unions, and mortgage insurers such as CMHC, Sagen, and Canada Guaranty, generally require appraisal reports completed by AIC members in compliance with CUSPAP. Reports prepared by non-members are typically not accepted for institutional lending purposes.

Why Vancouver Island Mortgage Brokers Specify AIC Appraisers

For Vancouver Island mortgage brokers, choosing an AIC-designated appraiser is not just a preference. It is a practical requirement for getting files approved by lenders who expect compliant, professionally prepared reports.

There are several reasons experienced brokers return to the same appraisal firm for every file.

  • Professional accountability – AIC members are subject to a complaint and discipline process administered through the AIC and its provincial affiliates. That accountability matters when a lender relies on a report to support a significant credit decision.
  • Consistent reporting standards – CUSPAP-compliant reports follow a recognized structure that lenders can evaluate. Consistent format reduces the back-and-forth that delays closings.
  • Recognized credentials – When a lender review team sees AACI or CRA after an appraiser’s name, they know the report meets a national professional standard. That recognition smooths the review process.
  • Reduced risk of file rejection – A report that does not meet lender requirements can stall or kill a deal. Working with an established, credentialed firm reduces that risk for brokers and their clients.

Local Market Knowledge Across Southern and Central Vancouver Island

Designation alone does not make an appraisal useful. An appraiser who is unfamiliar with Vancouver Island property markets may produce a technically compliant report that still fails to accurately reflect local conditions. That kind of report can draw questions from lenders and create headaches for brokers.

Southern and Central Vancouver Island covers a wide range of communities and property types. From character homes in Oak Bay and infill builds in Victoria to rural acreages in the Cowichan Valley and waterfront properties on the Gulf Islands, each sub-market has its own dynamics. An appraiser with deep, active experience across this geography produces valuations that reflect genuine local conditions, not imported assumptions.

For brokers working in Nanaimo, Parksville and Qualicum, or the Comox Valley, this regional expertise is especially important. The comparable sales that support a valuation in Comox look very different from those supporting a valuation in Langford. An appraiser who knows both markets can select and adjust comparables with confidence.

What Mortgage Brokers Should Look for in an Appraisal Partner

Not every appraisal firm is equally well suited to consistently serve Vancouver Island mortgage brokers. When evaluating a potential appraisal partner, it is worth asking a few direct questions.

  • Are all appraisers members in good standing with the Appraisal Institute of Canada (AIC)?
  • Does the firm have active experience across the communities where your clients are buying?
  • Can the firm deliver reports in a timely manner that fit your clients’ closing timelines?
  • Are reports produced in a clear format that lenders can review without additional follow-up?

A firm that can answer yes to all four questions will protect your files and your professional reputation. The goal is accurate, comprehensive valuations delivered on time, every time.

Frequently Asked Questions

  • Do Vancouver Island mortgage brokers need to order the appraisal directly, or does the lender arrange it?
    In most cases, the mortgage broker orders the appraisal directly. Under AIC standards, the party who orders the report is the client, most often the broker, not the lender or borrower.
  • What is the difference between a CRA and an AACI appraiser for a residential mortgage file?
    For a standard residential mortgage on a property with up to four units, a CRA-designated appraiser is fully qualified. The AACI designation is required for commercial properties, multi-family buildings with more than 4 units, and other property types beyond standard residential. Both designations are issued by the Appraisal Institute of Canada and require adherence to CUSPAP standards.
  • How quickly can an AIC-designated appraiser on Vancouver Island typically turn around a mortgage appraisal report?
    Turnaround times vary by firm and property type. Established local firms serving Southern and Central Vancouver Island generally aim to deliver reports promptly to meet lender deadlines. Brokers working with time-sensitive files should confirm turnaround expectations directly with the appraisal firm before assigning the file.

Work with D. Fritz Appraisals for Your Vancouver Island Mortgage Files

Fritz Appraisals is a long-established
residential appraisal firm serving Southern and Central Vancouver Island, from Victoria to the Comox Valley and the Gulf Islands of British Columbia. All appraisers are members in good standing with the Appraisal Institute of Canada (AIC), and our reports are produced in a clear format that meets lender requirements.

For Vancouver Island mortgage brokers who need fast, accurate, lender-accepted appraisals, we offer the local expertise and professional credentials to support every file. Call us at 250-413-7319 or D. Fritz Appraisals on Google to connect with our team.

home value calculator

Home Appraisals vs. Online Home Value Calculators for Vancouver Island Homeowners

Understanding the Difference Between Professional Appraisals and Automated Estimates on Vancouver Island

When you use a home value calculator, you get an instant estimate with very little effort, but is that number actually reliable? Whether you are trying to figure out what your property may be worth before listing it, refinancing, or simply satisfying curiosity, the tool you choose matters more than most homeowners realize.

You can hire a certified appraiser who will spend time thoroughly evaluating your property, or you can type your address into an online calculator and get a result in seconds. Both approaches claim to tell you what your home is worth, but they differ significantly in accuracy, reliability, and the situations in which each is appropriate.

Key Takeaways

  • Professional appraisals – certified experts visit your property in person, while an online home value calculator relies on algorithms that pull data from public records.
  • Accuracy – Appraisals deliver more accurate results because the appraiser can assess your home’s unique features firsthand. Online tools offer convenience, with instant estimates available at any time.
  • Cost and speed – Online home value calculators are free and return results immediately. Professional appraisals are a worthwhile investment, with fast turnarounds.
  • When each tool applies – You will often need a professional appraisal for mortgage applications, legal matters, and estate planning. An online home value calculator works well when you simply want a general idea of what your property might be worth.
  • Unique and renovated properties – Professional appraisers are especially helpful here. Online calculators often struggle because their data may be outdated, and they cannot account for a home’s current condition or recent upgrades.

What Is a Professional Home Appraisal?

A professional home appraisal is an independent evaluation of your property conducted by a certified appraiser. Unlike an online home value calculator, an appraisal involves an in-person visit where the appraiser examines your home’s condition, age, size, layout, and any upgrades or renovations you have completed. They also research your local neighbourhood, review zoning considerations, and compare your property against similar homes that have sold recently in your area.

Appraisals are commonly required for mortgage approvals, real estate transactions, estate planning, legal disputes, and tax-related decisions. Lenders often depend on these impartial evaluations when deciding whether to approve a loan and how much to approve. Canadian appraisers must adhere to professional standards. D. Fritz Appraisals is a member of the Appraisal Institute of Canada, and all of our appraisers are members in good standing with the AIC, ensuring our work meets a high standard of quality and objectivity.

The result is a formal report that documents your property’s market value as of a specific date, providing solid, defensible documentation for important financial and legal decisions.

What Is an Online Home Value Calculator?

Also called an Automated Valuation Model (AVM), they use computer algorithms to generate a rough estimate of a property’s value based on publicly available information. These tools scan data sources such as tax assessments, recent sales in the neighbourhood, and basic property characteristics such as square footage and lot size.

Common data sources used by a home value calculator include:

  • Public records (such as BC Assessment) and municipal tax assessments
  • Recent neighbourhood sales and broader market trends
  • General property details such as square footage, lot size, and number of bedrooms

Popular platforms use slightly different methods, which is why you will often see different figures for the same property depending on which tool you use. While these calculators are free and convenient, they cannot account for the things that truly differentiate one home from another, such as the quality of a recent renovation, the condition of the roof, or a particularly desirable view.

Key Differences in Methodology and Accuracy on Vancouver Island

The most important distinction between a professional appraisal and an online home value calculator lies in how each gathers and weighs information.

A certified appraiser physically inspects your property and applies professional judgement to factors that no algorithm can replicate. They consider neighbourhood nuances, the actual condition of your home, and the quality of any improvements. Appraisals follow standardized guidelines that ensure consistency, thoroughness, and accountability.

By contrast, a home value calculator works entirely with numerical data pulled from public records. It cannot see inside your home, identify deferred maintenance, or recognize that your kitchen was fully renovated last year. When the data feeding the algorithm is outdated or incomplete, the estimate suffers accordingly. This is particularly relevant across Vancouver Island, where rural areas, Gulf Islands properties, and unique waterfront homes lead to the widest gaps between calculator estimates and true market value.

Strengths and Limitations of Each Approach

Home value calculators offer:

  • Instant results available any time of day, at no cost.
  • A useful starting point for general property research.
  • The ability to track general value trends over time.

It’s limited by:

  • Potentially outdated or incomplete public records data.
  • An inability to assess your home’s actual condition or unique features.
  • No standardized methodology or professional accountability.
  • A significant margin of error, especially for unique or rural properties.

A professional appraisal offers:

  • A thorough, in-person evaluation by a credentialed expert.
  • Compliance with professional standards often required by lenders and courts.
  • Consideration of unique features, conditions, and local market nuances.
  • A formal, defensible report for financial and legal purposes.

The trade-off is straightforward: appraisals take more time and carry a cost, while a home value calculator is immediate and free but far less precise.

When to Use Each Option

Choosing the right tool depends on what you need the valuation for and how much accuracy matters.

Choose a professional appraisal when:

  • Applying for a mortgage or refinancing your home
  • Buying or selling a property, which requires a precise, credible value
  • Handling estate planning, a divorce settlement, or a legal dispute
  • Your property has undergone significant renovations or has unique characteristics
  • Your neighbourhood has changed considerably in recent years

Use an online home value calculator when:

  • You are casually curious about your property’s general worth
  • You want to monitor market trends in your area over time
  • You are doing early-stage research before speaking with a real estate professional

For any decision that has significant financial or legal consequences, a professional appraisal is the appropriate choice. An online home value calculator simply does not provide the depth or reliability needed when the stakes are high.

Frequently Asked Questions

  • How Far Off Can An Online Home Value Calculator Be?

Accuracy depends on both the property and the market. In areas with plenty of recent, high‑quality sales data, some online valuation tools can sometimes fall within a single‑digit percentage range of market value on average. On Vancouver Island – especially in rural areas, on island properties, or for unique homes – the margin of error for an individual property can be much wider, and online estimates should be treated as rough approximations rather than precise values.

  • How Often Should I Get a Professional Appraisal?

There is no fixed schedule, but you should consider a professional appraisal any time you are making a major financial decision involving your property. Significant renovations, refinancing, estate planning, and property tax disputes are all common triggers. Between formal appraisals, a home value calculator can give you a general sense of market movement, but it should not replace professional advice when money or legal matters are involved.

  • What Factors Does a Home Value Calculator Typically Miss?

Online calculators cannot assess the quality of renovations, the condition of major systems like the roof or HVAC, curb appeal, interior finishes, lot orientation, or neighbourhood micro-factors. They also struggle when comparable sales data is limited. A certified appraiser considers all of these elements during an in-person evaluation.

Get an Accurate Home Appraisal on Vancouver Island

While an online home value calculator is a convenient starting point for casual research, it is no substitute for the accuracy and reliability of a professional appraisal when it matters most. At D. Fritz Appraisals, our certified appraisers serve homeowners across Victoria, Vancouver Island, and the Gulf Islands with thorough, impartial property evaluations that meet professional standards.

Whether you are buying, selling, refinancing, settling an estate, or navigating a legal matter, our team delivers the precise, credible valuations that lenders, lawyers, and courts can rely on.

Call us at 250-413-7319 or visit dfritzappraisals.ca/contact/ to book your home appraisal and get the accurate property value you need to move forward with confidence.

Understanding the Role of Appraisals for Mortgage Refinancing On Vancouver Island

Understanding the Role of Appraisals for Mortgage Refinancing on Vancouver Island

Mortgage Refinancing: Your Essential Appraisal Guide for Vancouver Island Homeowners

When you’re considering mortgage refinancing in Victoria and across Vancouver Island, an appraisal is a critical step that helps determine your loan terms, interest rate, and whether you get approved. During this process, a professional appraiser visits your home to assess its current market value by examining its condition, size, and location, and comparing it to recently sold properties in your neighbourhood.

Knowing this value is essential because lenders use it to calculate how much they’re willing to lend you. A lower-than-expected appraisal could complicate your refinancing plans, while a higher appraisal might help you access better rates or borrow more against your home’s equity.

Key Takeaways

  • Appraisals provide an independent property valuation to ensure your refinancing loan doesn’t exceed what your home is actually worth on the market.
  • Lenders rely on appraisals to assess risk and determine the appropriate loan terms, interest rates, and approval amounts for your mortgage refinancing.
  • Appraisers evaluate your property and compare it to recently sold similar homes in your neighbourhood to determine its market value.
  • Homeowners can boost their appraisal values by completing repairs, adding fresh paint, improving curb appeal, and ensuring all systems function properly.
  • Low appraisals can be challenged through value reconsiderations, a second appraisal, or adjustments to your refinancing strategy with your lender.

What Is a Refinance Appraisal and Why Do Lenders Require One?

When you apply for mortgage refinancing, your lender will require a refinance appraisal: an independent evaluation that determines your property’s current market value. This unbiased assessment ensures the loan amount doesn’t exceed your home’s actual worth, protecting both the lender and the borrower.

Lenders use this appraisal to evaluate the risk of approving your new mortgage. The results directly influence your loan terms and conditions, including interest rates and approval amounts. A licensed appraiser, like the team at D. Fritz Appraisals, will use their experience with the local Victoria and area market to provide you with a comprehensive report that will meet the demands of your lender. As designated members of the Appraisal Institute of Canada (AIC) and insured in accordance with CUSPAP, our team delivers accurate, lender-ready valuations with fast turnaround times.

If the appraisal comes in below expectations, you may face complications, including higher costs or the need to renegotiate loan terms with your lender.

What Happens When the Appraiser Visits Your Home?

During the appraiser’s visit, you’ll see a thorough evaluation of your property that goes well beyond a simple walkthrough. The appraiser will carefully assess your home’s size, layout, and overall condition, paying close attention to essential systems like plumbing and HVAC. They’ll document any upgrades or renovations you’ve completed, as these improvements can significantly boost your property’s market value.

The evaluation extends beyond your property’s walls. The appraiser will examine your neighbourhood’s characteristics and desirability factors that influence your home’s worth. Once the inspection concludes, the appraiser compiles their findings into a comprehensive report for your lender’s review.

How Do Appraisers Calculate Your Property’s Market Value?

Understanding your property’s market value starts with a careful, thorough assessment that considers both the property itself and the local market conditions around it.

Your appraiser considers critical factors that impact your home’s worth:

  • Location advantages – factors that enhance your property’s desirability and future potential
  • Neighbourhood characteristics – that reflect the community you’ve built your life in
  • Essential home systems – including plumbing and HVAC that improve comfort and safety
  • Proximity to amenities – that make daily life convenient for your family
  • Market trends – that affect your investment’s current and future value


The final appraisal report details the methodology and justifies the assessed value with thorough data analysis. As a company approved for most financial institutions, including banks, credit unions, and private lenders, D. Fritz Appraisals understands exactly what each lender needs from a report – and delivers it in a clear, timely manner.

Simple Repairs and Updates That Increase Appraisal Value

Before your appraiser arrives, you’ll want to make small repairs that can significantly boost your home’s value. Fix leaky faucets, replace worn-out light fixtures, and add fresh paint in neutral colours to make rooms feel larger and more welcoming. These simple updates show appraisers that you’ve maintained your home properly.

Don’t forget about your home’s exterior. Trim hedges, plant flowers, and improve your landscaping to increase curb appeal; it’s essential for making a great first impression. Consider upgrading older appliances to energy-efficient models to show your home is modern and reduce future utility costs.

Ensure all systems, including electrical, are functioning properly and meet current code requirements. Properly functioning, up-to-date systems prevent negative comments in the appraisal report and help secure a higher valuation, which directly affects your mortgage refinancing terms.

What Are Your Options if the Appraisal Comes in Low?

Even after completing repairs and updates, your appraisal might still come in lower than you hoped. Don’t panic; you have several solid options to address this setback:

  • Review the appraisal report – carefully check for errors or mistakes that may have unfairly lowered your property’s value.
  • Submit a value reconsideration – provide your lender with strong evidence, such as recent comparable sales, to support a higher appraisal.
  • Request a second appraisal – at your own cost if you’re confident the first assessment was incorrect.
  • Adjust your refinancing strategy – consider a smaller loan amount or explore different lenders with more flexible requirements.
  • Renegotiate terms – speak with your lender if the appraisal value significantly affects your loan approval process.

Acting quickly gives you the best chance of achieving your mortgage refinancing goals.

Frequently Asked Questions

  • How Long Does the Refinance Appraisal Process Take?
    A physical inspection typically takes less than 20 minutes for a single-family home, depending on its size. After the visit, appraisers promptly deliver the completed report to your lender, ensuring your refinancing process proceeds without unnecessary delays. Complex properties or challenging market conditions may slightly extend this timeline.
  • Can I Be Present During the Appraisal?
    Yes, you can be present during the appraisal, and it’s often beneficial. You can highlight recent upgrades, answer questions about your property, and provide documentation of renovations. However, avoid hovering or attempting to influence the appraiser’s professional judgment.
  • Can Market Changes Affect My Appraisal if I Refinance Later This Year?
    Yes. Appraisals reflect current market conditions at the time of inspection. Seasonal demand, interest rate shifts, and recent sales activity in Victoria and surrounding areas can all influence value, so refinancing sooner or later may yield different results.

Work With Victoria’s Trusted Appraisal Professionals

Navigating the appraisal process for mortgage refinancing doesn’t have to be stressful when you work with experienced professionals who know the Victoria market inside out. A thorough, accurate appraisal protects your interests and helps ensure your refinancing goes smoothly.


At D. Fritz Appraisals, we bring decades of local expertise to every appraisal. As designated members of the Appraisal Institute of Canada (AIC) and professionally insured in accordance with the Canadian Uniform Standards of Professional Appraisal Practice (CUSPAP), we provide sound, accurate valuations you and your lender can rely on.

Whether you’re refinancing in Victoria, Saanich, Oak Bay, or the surrounding communities, our team delivers comprehensive, lender-ready reports with the fast turnaround times our clients count on.

Ready to move forward? Contact D. Fritz Appraisals today to get a fast, accurate appraisal from a team that knows the Victoria market. Find us on Google or call us at 250-413-7319.


How to Get the Best Appraisal for Investment Properties in Victoria

How to Get the Best Appraisal for Investment Properties in Victoria

Residential Investment Property Expertise Throughout Victoria

An accurate investment property appraisal is essential for understanding the true value of your residential real estate portfolio. Whether you’re buying, selling, or refinancing rental properties on Vancouver Island, proper preparation can significantly impact your valuation. From property maintenance to gathering documentation, the work you do beforehand sets the stage for success. Let’s explore how you can position your investment properties for the best possible appraisal outcome.

Key Takeaways

  • Thorough preparation of your property, including making repairs and improving curb appeal, helps create a positive first impression for the appraiser.
  • Gather complete documentation, including lease documents/rent rolls, tax records, renovation receipts, and related operating expenses, to support your property’s value.
  • Showcase recent upgrades, renovations, and property improvements with before-and-after documentation to demonstrate the added value to your investment.
  • Research comparable property sales in your area to understand the market context and share relevant information with your appraiser.
  • Select a qualified appraiser who has experience with residential investment properties and understands income-based valuation methods, so your property’s income potential is properly reflected in the local market.

How a Qualified Appraiser Can Help With Investment Property Experience

When you’re investing in residential real estate in Victoria, working with a qualified appraiser, such as D. Fritz Appraisals, can significantly impact your return on investment. A professional appraiser provides accurate, fair-value assessments of rental properties. They’ll assess potential returns, analyzing expected rental income and current market conditions specific to your property. 

An appraiser’s expertise helps you understand local market dynamics, including rental rate trends and property values throughout Vancouver Island and the Gulf Islands. This knowledge is particularly valuable for investors in residential and rental properties on Vancouver Island who wish to grow their portfolios and build long-term wealth.

Preparing Your Investment Property for Maximum Appraisal Value

Although many investors focus on market conditions, properly preparing your rental before an appraisal can help ensure that all value-supporting features are recognized. Attention to presentation and maintenance will significantly impact an appraiser’s assessment of your investment property.

Make all necessary repairs, from small issues such as leaky faucets to structural problems that could reduce your valuation. Improve curb appeal through landscaping and exterior work, as first impressions strongly influence appraisers’ judgments.

Essential Documents and Information to Provide Your Appraiser

When appraisers determine the value of your residential investment property, proper documentation makes a significant difference. First, collect your property title to prove ownership and to show any legal limits or rights-of-way and bring the recent property tax bill.

Gather receipts for any renovations, as these upgrades often substantially boost property value. A detailed rent roll, including current and past income, and lease agreements demonstrates the revenue you can generate. This income documentation is particularly critical for appraisal purposes, as it directly impacts valuation calculations.

Finally, research recently sold properties with similar attributes nearby, as it may help the appraiser better establish an accurate market baseline. All these documents provide a complete picture for a more accurate, well-supported appraisal.

Understanding Different Appraisal Methods for Investment Properties

To ensure your residential investment property receives a thorough valuation, you need to understand the various methods appraisers use to determine its worth. There is no single method that works for every property, and appraisers typically combine approaches based on property characteristics and market conditions.

  • Direct Comparison Approach: compares your property to similar recently sold properties, adjusting for differences in features and market conditions. This method works well in active markets with ample comparable sales data and often carries significant weight in smaller residential rentals.
  • Income Approach: estimates value based on potential income generation, considering rental income, expenses, and capitalization rates. Commonly used in commercial real estate investing, this approach ensures your property’s income potential is accurately reflected in its valuation.
  • Gross Rent Multiplier (GRM): provides a quick valuation by dividing the property price by gross rental income. This is often used for simpler residential rental screening and initial assessments of investment properties on Vancouver Island.

Professional appraisers weigh each approach based on your specific property type, local market data, and investment characteristics to arrive at an accurate, fair-market-value opinion.

Leveraging Appraisal Results for Strategic Investment Decisions

After receiving a comprehensive appraisal of your investment property, you’ll have a valuable tool to help you make better choices. Your assessment will show your property’s real market value, helping you make informed decisions when it comes to buying or selling.

Put your appraisal results to work by estimating your potential return on investment. Review the projected rental income and the property’s potential appreciation. When you understand components such as the income approach and the sales comparison approach, you can see what’s really driving your property’s value.

Don’t file your appraisal away after initial use. Review it regularly when assessing your property portfolio to make informed decisions about property improvements, management changes, or whether you should sell. This ongoing analysis ensures your residential investment properties continue to perform optimally and meet your financial objectives.

Frequently Asked Questions

  • How Long Does A Residential Investment Property Appraisal Take?
    On Vancouver Island, the final report typically follows within 7 days after inspection. The appraiser will spend 30 to 60 minutes on the physical inspection, then conducts a comparative market analysis, analyzes rental income data, and prepares a comprehensive report. Properties with multiple units or unique features may require additional time.
  • Do I Need an Appraisal When Refinancing My Rental Property?
    Most lenders require a current appraisal when refinancing residential investment properties, even if you’ve had one done previously. Lenders need to verify the current market value to determine the loan-to-value ratio. A fresh appraisal accounts for market changes, improvements, and the current potential for rental income.
  • What’s The Difference Between An Appraisal And A Property Assessment For Investment Properties?
    BC Assessment provides annual assessed values for property tax purposes based on a standardized mass appraisal. A professional appraisal is an independent, detailed analysis of your property’s current market value, considering recent sales, condition, upgrades, and income potential. Lenders and investors rely on professional appraisals for financing and purchase decisions because they provide more current, property-specific valuations.

Get Your Investment Property Appraisal 

At D. Fritz Appraisals, we understand how important it is to receive an accurate valuation of your residential investment properties, so you can make informed choices that maximize your returns.

Our appraisers are certified by the Appraisal Institute of Canada (AIC) and are professionally insured for liability in accordance with the Canadian Uniform Standards of Professional Appraisal Practice (CUSPAP). We’re here to deliver peace of mind with an accurate, independent, and professionally prepared appraisal. With decades of experience serving our clients on Vancouver Island and the Gulf Islands, we deliver the local market expertise you need. 

When you’re ready to move forward with your investment property goals, reach out to D. Fritz Appraisals to book your professional appraisal.

Community Amenities and impact on home value

Community Amenities and Their Influence on Home Value

The Value of Strong Community Amenities

When determining your home’s value, the quality and variety of community amenities surrounding your property play a major role. It’s not only the size or style of your house that matters. Factors such as nearby schools, parks, walkability, transportation, and infrastructure all contribute to a neighbourhood’s desirability. These community amenities enhance everyday living while helping properties maintain or increase their value over time.

As appraisers serving Greater Victoria and Vancouver Island, we see every day how these community features influence both immediate sale prices and long-term investment returns. When you buy a home, you are investing in a lifestyle that extends beyond your property line.

Key Takeaways

  • Schools: Proximity to schools has a measurable effect on home value.
  • Parks and green space: Access to parks consistently raises property appeal and strengthens long-term stability.
  • Walkability and transit: Neighbourhoods that offer easy access to transportation and services tend to show stronger home values.
  • Local amenities: Shops, cafés, and restaurants help shape vibrant communities and contribute to steady property appreciation.
  • Safety and infrastructure: Well-maintained roads, sidewalks, and utilities, along with neighbourhoods with lower crime rates, support healthy market values.

Schools and Educational Facilities Drive Property Values

In British Columbia, school catchment boundaries are closely tied to housing demand. Research from the University of British Columbia found that changes in public-school catchment areas are directly reflected in surrounding property prices. Families often prioritize school access when choosing where to live.

Homes within desirable school catchments frequently sell faster and retain a higher assessment value. For buyers and investors, living near schools offers both convenience and long-term financial security.

Parks and Green Spaces Create Lasting Appeal

Across British Columbia, proximity to parks and natural spaces remains one of the most sought-after community amenities influencing property value. In Greater Victoria, parks such as Beacon Hill, Mount Douglas, and Thetis Lake are more than beautiful backdrops; they are part of the lifestyle that defines the region.

Homes near green spaces tend to attract greater interest because they offer a balance between nature and city living. Residents value the ability to step outside for a morning walk, enjoy family picnics, or simply take in the views that make Vancouver Island unique. These daily experiences contribute to both a higher quality of life and stronger neighbourhood pride.

From an appraisal perspective, access to green space is often viewed as a long-term value stabilizer. Well-maintained parks create healthy, connected communities that remain desirable over time. For many homeowners, living near these natural areas adds comfort and peace of mind. 

Walkability and Transportation Access Enhance Market Desirability

Walkability and transit connectivity are important to consider in BC’s housing market. Market research shows that homes in walkable areas generally command higher prices and maintain stronger long-term growth.

Victoria’s average walk score is 76, meaning most errands can be completed on foot. Neighbourhoods such as Harris Green, Downtown, and Fernwood consistently outperform less connected areas because of their easy access to restaurants, shops, and transit.

When public-transport routes, bike paths, and pedestrian networks are nearby, buyers see greater value and convenience. Properties that combine accessibility with other community amenities typically maintain higher home values, even during market fluctuations.

Shopping and Dining Options Boost Neighbourhood Worth

Access to retail and dining options is another factor that strengthens both livability and value. In Victoria, areas like Cook Street Village, Quadra Village, and Oak Bay Avenue illustrate this connection perfectly. These districts blend small-business charm with walkable streets and community character, creating places where people genuinely want to live.

Properties within walking distance of shops, coffee spots, and restaurants appeal to a wide range of buyers, from families to professionals and retirees. The presence of these community amenities not only enhances daily life but also supports long-term market resilience.

Safety, Infrastructure, and the Value of Community Amenities

Neighbourhood safety and infrastructure are essential community amenities that shape how buyers view a property’s long-term potential. Well-maintained roads, reliable utilities, and effective waste management systems foster trust and stability, which directly support neighbourhood desirability.

Communities with strong public services and low crime rates tend to maintain higher property values because they foster security and confidence among residents. In Victoria, continued investments in infrastructure, including improved public transit, expanded cycling routes, and revitalized public spaces, highlight the city’s ongoing commitment to livability.

These enhancements are more than functional upgrades. They are lasting community amenities that improve daily life, encourage local engagement, and protect property value for years to come.

Frequently Asked Questions

  • How Do Community Amenities Influence A Professional Property Appraisal?
    During an appraisal, factors such as proximity to schools, access to parks, and neighbourhood infrastructure are reviewed alongside the home’s condition and size. These community amenities often determine a location’s desirability and can influence comparable sales and overall market positioning.
  • Why Are Walkability And Transit Access Considered Key Community Amenities?
    Walkability and reliable public transportation improve accessibility, reduce commuting time, and encourage a sense of neighbourhood connection. Properties located in walkable areas or near transit lines are often seen as more desirable because they make daily life easier and more sustainable.
  • How Can Homeowners Showcase The Value Of Nearby Community Amenities When Selling?
    Highlighting local features, such as nearby schools, trails, markets, or playgrounds in listings and marketing materials, helps buyers visualize the lifestyle that comes with the home. These community amenities can make a property stand out and justify a higher asking price.


Helping You Understand How Community Amenities Shape Market Value

When evaluating or purchasing a home in Greater Victoria, it is essential to look beyond the property’s four walls. The schools your children attend, the parks you visit, and the convenience of your daily commute all shape your home’s financial outlook.

Neighbourhoods with strong community amenities consistently demonstrate better market performance and higher BC assessment home values. These features make communities more livable, enjoyable, and enduring.

At D. Fritz Appraisals, we help homeowners, lenders, and buyers understand how community amenities influence real estate value across Vancouver Island. A professional appraisal considers not only the property’s physical structure but also the surrounding amenities that make a neighbourhood thrive.

When it comes to protecting your investment, recognizing the power of community is one key to understanding true property value. Our appraisers are certified by the Appraisal Institute of Canada (AIC) and professionally insured for liability, in accordance with the Canadian Uniform Standards of Professional Appraisal Practice (CUSPAP). Contact us today to get started on your comprehensive valuation.

Home Appraisal for Divorce

Home Appraisal in Divorce: What Every Homeowner Should Understand

The Importance of Getting a Fair House Appraisal for Divorce

A home appraisal in divorce is essential when you and your spouse need a clear, impartial number to support a fair division of property. The family home is often the largest shared asset, and relying on online estimates or informal opinions can lead to costly disagreements. A certified appraisal establishes the current market value in an objective, legally credible, and practical manner for negotiations or court submissions. For couples in Southern and Central Vancouver Island, including Victoria, Nanaimo, and the Gulf Islands, selecting a local firm with in-depth market knowledge ensures your home’s value accurately reflects the local market conditions.

Key Takeaways

  • A certified home appraisal provides an unbiased assessment of market value, supporting a fair division of assets.
  • Courts and mediators rely on professional reports that meet Canadian appraisal standards and are prepared by members of the Appraisal Institute of Canada.
  • A house appraisal for divorce is critical for buyouts, legal settlements, and court requirements.
  • Retrospective valuations can establish property value as of the separation date or prior to significant post-separation improvements.
  • Local market expertise enhances accuracy and ensures the appraisal accurately reflects the local market.

Why an Appraisal Matters During Divorce

During separation, emotions can complicate financial decisions. A home appraisal for divorce brings clarity by focusing on comparable sales, neighbourhood trends, property conditions, and current listings. With a professional report in hand, both homeowners can negotiate from a common foundation, which reduces the likelihood of conflict and shortens the time to reach an agreement. Because the real estate market is constantly evolving, an independent appraisal ensures that decisions are made using current, local data rather than estimates.

How a House Appraisal for Divorce Works

Your appraiser inspects the property, reviews recent sales of similar homes, considers market direction, and evaluates unique features or deferred maintenance. The result is a detailed, written report that explains the methods used, the comparable properties analyzed, the adjustments made, and the final opinion of value. For divorcing couples, the report is formatted so that lawyers, mediators, lenders, and the court can understand the rationale and adopt it as a credible basis for settlement discussions.

When an Independent Valuation Becomes Essential

There are several common moments in a divorce when an independent home appraisal becomes essential. 

  • If one homeowner wants to keep the home and buy out the other, the appraisal supports a fair buyout figure. 
  • If there is disagreement about the property’s worth, a neutral valuation helps focus the dispute on the facts. Courts may also require professional documentation to advance the proceedings. 
  • For situations where the separation occurred months or years earlier, a retrospective valuation can determine the value as of the separation date, excluding the effect of significant improvements completed after the separation, so that both parties are treated fairly. 

Special Situations That Affect Value

Some divorces involve properties that earned rental income before or after separation. In such cases, an accurate valuation aids in tax planning and capital gains considerations. You may need a current valuation and a second retrospective valuation to align with the date when rental income began.

Working with an appraiser who understands the local market history is especially valuable in these scenarios, since long-running trends can influence the numbers. 

What to Expect in the Report

A well-prepared home appraisal in a divorce report clearly explains:

  • The scope of work
  • Describes the property
  • Details the data sources and comparable sales
  • Presents a well-reasoned value conclusion

The document stands on its own, with transparent reasoning and attachments that support the figures presented.

Lawyers and mediators appreciate reports that meet professional standards, because they can be submitted to the court when needed without rework or delay. The clarity of the analysis reduces the chance of later challenges and gives both spouses confidence in the outcome. 

Protecting Both Parties Through an Unbiased Evaluation

Dividing a family property and assets is a complex process. At D. Fritz Appraisals, we’re here to ensure you have the information you need about your home’s value to come to a fair and amicable agreement.

Instead of debating a price range pulled from online tools or neighbourhood chatter, you both rely on a professionally supported value. The neutrality of the report helps negotiations stay focused on solutions, such as buyouts or timelines for sale, rather than on disputes about price. That objectivity is why courts and lenders continue to rely on certified appraisers for matters involving divorce settlements. 

Frequently Asked Questions

  • Can A Home Appraisal Be Backdated To The Separation Date?
    Yes. This is known as a retrospective appraisal, which establishes the property’s value as of the legal date of separation. It’s often required for court or settlement purposes when the divorce process takes place months or even years after separation.
  • Is One Appraisal Enough If My Spouse Disagrees With The Value?
    If there’s a dispute, both parties may order their own appraisals. However, courts typically prefer when a single independent certified appraisal is agreed upon, as this reduces conflict and costs.
  • What’s The Difference Between A Market Valuation And An Appraisal For Divorce?
    A market valuation from a realtor provides an estimate of what the home could sell for, but it is not considered legal evidence in divorce proceedings. A certified appraisal produces a formal report that meets Canadian standards and is accepted by the courts.

Ensuring Fairness in Property Division

A home appraisal in divorce gives you and your spouse a reliable number that supports fair decisions and reduces conflict. At D. Fritz Appraisals, we understand how important it is to receive a fast and accurate appraisal of your family property, so you can focus on moving forward. 

All appraisers at D. Fritz Appraisals are certified with the Appraisal Institute of Canada (AIC) and professionally insured for liability according to the Canadian Uniform Standards of Professional Appraisal Practice (CUSPAP), providing peace of mind that your appraisal is accurate, impartial, and professionally prepared. When you are ready to move forward, reach out to D. Fritz Appraisals to book your professional appraisal and take the next step toward a fair settlement.

Estate Planning Mistakes

Estate Planning Mistakes Property Owners Can’t Afford to Make

Common Property Valuation Pitfalls That Threaten Estate Plans

Estate planning requires careful property valuation to ensure your assets transfer smoothly to your beneficiaries. You’ve worked hard to build your wealth, but a few common mistakes can harm even the most thoughtful estate plan. Incorrect property assessments often lead to family disputes, unfair distributions, and unexpected tax burdens that could have been avoided. What valuation errors might you be making right now that could put your legacy at risk?

Key Takeaways

  • Using old property valuations leads to wrong estate sharing and possible tax problems, including higher probate fees.
  • Failing to account for future market changes can lead to unfair distributions among your heirs over time.
  • Missing information, like structural problems or shoreline erosion, can throw off your valuation.
  • Overlooking the tax effects of property transfers can greatly reduce the value your heirs receive, especially concerning capital gains on non-principal residences.
  • Not seeking advice from qualified professionals for both appraisals and legal/tax planning.

Relying on Outdated Property Valuations

When planning your estate, using outdated property valuations can create major problems for your beneficiaries. Vancouver Island’s real estate market changes all the time, and values from just a year ago might not match today’s market.

Effective estate planning in BC requires current appraisals that accurately reflect your property’s value. Old valuations can lead to tax errors, unfair asset distribution, and potential friction among heirs.

Your estate might face unnecessary probate delays or increased probate fees if government assessments are very different from your documented values. In British Columbia, probate fees are calculated based on the gross value of the estate, so an accurate, up-to-date appraisal is crucial to avoid overpayment.

We suggest updating your property appraisals every 1-2 years, or whenever significant market changes occur. Professional appraisals provide the accurate documentation needed for proper estate administration and help prevent disputes among beneficiaries. Proper documentation ensures your estate plan accurately reflects current market values and your legacy is distributed according to your wishes, without complications for your loved ones.

Neglecting to Consider Future Market Trends

Although current valuations are crucial, overlooking future market trends can significantly undermine your estate planning efforts. The real estate market from Victoria to Nanaimo and beyond isn’t static, and your estate plan shouldn’t be either.

When you’re planning for property distribution, don’t just look at today’s numbers. Consider development proposals in neighbouring areas, infrastructure projects, and demographic shifts that could impact values in 5-10 years. Vancouver Island’s limited geography means potential growth areas command premium future values.

Many property owners mistakenly focus exclusively on current appraisals without considering projected market direction and how it might influence their decision to sell or hold onto the property. 

Overlooking Property-Specific Depreciation Factors

Property owners often overlook specific depreciation factors that can significantly impact the estate valuation of their property. When planning your estate, don’t ignore issues like delayed maintenance, outdated systems, or structural problems that can seriously lower your property’s value.

On Vancouver Island, factors such as coastal erosion, saltwater exposure, and the wear and tear on certain building materials require careful review.

You’re not helping your heirs by overestimating property worth based just on neighbourhood comparables.

Professional appraisers can identify these commonly overlooked depreciation elements that could impact your estate planning outcomes. A comprehensive value-added improvements assessment can help determine if renovations are worth pursuing before finalizing your estate plans.

Disregarding Tax Implications Associated With Property Transfers

When planning your estate, overlooking the tax implications associated with property transfers can lead to costly consequences for your heirs. Different transfer methods trigger various tax events, from capital gains on non-principal residences to probate fees that can greatly reduce the value of your legacy.

Upon a person’s passing in Canada, the Canada Revenue Agency (CRA) generally considers all capital assets (real estate, investments, etc.) to be “deemed disposed” at their fair market value immediately before death. This means that any increase in value (capital gain) from when the property was acquired until the date of death can trigger capital gains tax, which is paid by the estate. The significant exception to this rule is the deceased’s principal residence, which is typically exempt from capital gains tax.

However, for investment properties, recreational properties (cottages), or other secondary residences, these capital gains can represent a substantial tax liability for the estate. Additionally, British Columbia levies probate fees (also known as estate administration tax) on the gross value of the estate. Accurate and current property valuations ensure the correct amount is paid, avoiding overpayments or delays.

Don’t assume property values at the time of estate planning will remain static. Market changes can dramatically alter your tax liability picture.

Frequently Asked Questions

  • How Do Seasonal Market Fluctuations Affect Estate Property Valuations?
    Seasonal market fluctuations can significantly impact the value of your property. Summer often brings higher prices, while winter markets typically slow down. You’ll want to consider timing when planning your estate property valuations. It’s worth noting these patterns to optimize your property’s assessed value and navigate the Canadian real estate cycle with confidence.
  • How Does Rental Income Potential Influence Estate Planning?
    It boosts your property’s value, creates revenue streams for your beneficiaries, and can make some properties better inheritance assets than others. When planning your estate, properties that generate ongoing income might be more helpful for your heirs. A steady cash flow helps cover maintenance costs and taxes after you’re gone. Canadian tax rules around rental properties and inheritances are unique, so talking with a local financial advisor about maximizing these benefits makes good sense.
  • Can Family Members Provide Reliable Property Valuations for Estates?
    Family members typically aren’t the best choice for valuing estate properties. They usually lack the professional training needed and may be too emotionally invested in the property to provide a fair assessment. They could also have personal interests that affect their judgment. It’s smarter to hire professional appraisers who can provide neutral, legally acceptable valuations that withstand scrutiny.

Securing Your Legacy with Accurate Estate Planning Valuations

Don’t let your estate plan fall victim to these common evaluation mistakes. You’ll serve your heirs better by using valuations based on current market trends that  account for depreciation and future market conditions. 

Consult a professional appraiser like D. Fritz Appraisals to help you understand the tax implications associated with inheriting a house. Our appraisers have professional liability insurance in accordance with the Canadian Uniform Standards of Professional Appraisal Practice and the Appraisal Institute of Canada. 

When you take these precautions, you ensure a smoother transfer of assets and help prevent disputes among beneficiaries. A thoughtful property evaluation today creates peace of mind for tomorrow. Contact us today to discuss your estate appraisal needs and ensure your legacy is protected.

How to Improve Curb Appeal

How to Improve Curb Appeal: What Appraisers Notice

Improving Curb Appeal to Improve Home Value

First impressions matter—especially when it comes to your home’s appraisal—and knowing how to improve curb appeal can make all the difference. During the summer months, your property’s exterior becomes even more noticeable to appraisers. By focusing on specific elements that professionals look for, you can enhance your home’s curb appeal and potentially increase its appraised value.

Key Takeaways

  • Well-maintained landscaping with fresh mulch and seasonal flowers significantly improves curb appeal and appraiser impressions
  • Clean, damage-free exteriors can significantly improve your property’s appraised value
  • A welcoming entryway with updated hardware and appropriate lighting creates a positive first impression
  • Functional outdoor living spaces add value and appeal to potential buyers
  • Regular maintenance of driveways, walkways, and lawns demonstrates care for your property

Improve Your Curb Appeal with Landscaping and Garden Maintenance

Investing time in landscaping and garden maintenance doesn’t just enhance visual appeal—it can add meaningful value to your property. Well-maintained landscaping is consistently recognized as one of the top improvements that can increase your home’s market value, making it a worthwhile consideration when improving curb appeal.

Regular lawn care, including mowing, watering, and weeding, creates a neat appearance that appraisers notice during evaluations. Trimming overgrown shrubs and trees not only enhances visual appeal but also eliminates potential safety concerns.

Adding fresh mulch to garden beds provides a polished finish to your outdoor spaces. Including seasonal flowers and native plants enhances curb appeal while reducing maintenance requirements, making your property more attractive to both appraisers and potential buyers. Understanding which improvements add the most value can help guide your landscaping decisions.

Exterior Home Condition and Its Impact on Curb Appeal

Your home’s exterior condition significantly influences appraiser perceptions. A well-maintained exterior creates curb appeal that resonates with both appraisers and potential buyers.

Neglected maintenance issues, such as peeling paint or roof damage, can significantly decrease your appraised value. Conversely, clean siding and a well-kept yard can lead to a noticeably higher home appraisal. Appraisers particularly notice structural integrity, making roof and siding maintenance essential. Additionally, accurate property valuation becomes especially important during challenging circumstances, particularly with jointly-owned homes during separation or divorce.

Regular maintenance activities like power washing and fresh paint not only enhance curb appeal but also create positive impressions that can lead to higher appraisals.

Entryway Upgrades That Improve Curb Appeal

Your entryway serves as the introduction to your home, making it crucial to make a good impression. A clean, welcoming entrance creates a positive first impression that influences overall curb appeal assessment.

Consider refreshing your front door with a new coat of paint in a complementary colour. This relatively inexpensive improvement can significantly improve curb appeal.

Well-maintained hardware, including doorknobs and handles, demonstrates attention to maintenance details and improves aesthetic appeal. Adding warmth through strategically placed potted plants or seasonal decorations creates an inviting atmosphere for both appraisers and potential buyers.

Proper lighting improves safety while highlighting your home’s features during evening hours, positively affecting appraisal outcomes.

Improve Curb Appeal with Outdoor Living Areas

Thoughtfully designed outdoor living spaces can substantially enhance your property’s curb appeal and value. Appraisers look for well-defined areas such as patios, decks, and porches that add functional space and aesthetic appeal.

Creating comfortable seating areas, outdoor dining options, and incorporating decorative elements transforms your yard into an attractive extension of living space that appeals to potential buyers. Features like fire pits, outdoor kitchens, or pergolas not only elevate your outdoor areas but also reflect contemporary living trends valued by many purchasers.

Maintaining these spaces through regular cleaning and seasonal updates is essential, as appraisers evaluate both condition and appeal during their assessment.

Cleanliness and Tidiness to Improve Curb Appeal in Your Neighbourhood

Though seemingly minor, cleanliness and tidiness significantly impact an appraiser’s first impression of your property. A well-maintained exterior demonstrates property care that can influence valuation.

Maintaining a neat front yard without excessive decorations or items allows appraisers to focus on your home’s actual features. Clean windows and freshly painted doors further enhance curb appeal, potentially contributing to higher appraised values.

Your attention to these details will likely yield benefits during the appraisal process.

Frequently Asked Questions

How Can I Enhance My Driveway’s Curb Appeal Before an Appraisal?

To improve driveway appeal before an appraisal, thoroughly clean the surface and repair any visible cracks or stains. Consider adding decorative borders or edging for visual interest. A well-maintained driveway creates positive first impressions for appraisers and potential buyers.

Do Seasonal Decorations Impact Curb Appeal?

Yes, tasteful seasonal decorations can enhance curb appeal. Select well-coordinated, appropriate decorative elements that draw attention and create a welcoming atmosphere. Maintain balance and avoid overcrowding for optimal effect.

How Much Does Landscaping Affect Home Value?

Landscaping significantly impacts home value. Well-maintained yards with thoughtfully selected plants and features substantially improve curb appeal, increasing property attractiveness to potential buyers. Investment in quality landscaping typically provides an excellent return when selling your home.

Are There Specific Plants That Appraisers Prefer?

Appraisers generally favour low-maintenance native plants suited to your region. Vibrant flowers and strategically placed shrubs enhance curb appeal and property attractiveness. Ensure your landscaping presents as tidy and inviting to create positive impressions during evaluation.

Making the Most of Your Property

Enhancing your home’s summer curb appeal creates a meaningful impact on appraiser impressions. Knowing how to improve your curb appeal—through landscaping maintenance, exterior condition, entryway presentation, and well-designed outdoor living spaces—helps showcase your property’s best features. Attention to cleanliness and overall tidiness demonstrates property care that resonates with appraisers. By addressing these key elements, you’ll not only attract potential buyers but also potentially increase your property’s appraised value. 

We’re proud to offer exceptional services for our clients. We tailor our appraisal reports to meet the requirements of each lender, providing accurate, timely and thorough valuations put together by our highly experienced professional team.

For more information or to schedule an appraisal, contact us today!

Sustainable Development Projects in British Columbia

Sustainable Developments: Shaping British Columbia’s Future

British Columbia continues to lead Canada in sustainable innovation, reshaping how we build, live, and interact with our environment. Across the province, forward-thinking real estate and infrastructure projects are integrating green design, low-carbon technologies, and Indigenous partnerships to create communities that thrive both now and in the future.
From groundbreaking residential developments to neighbourhood-scale sustainability models, these projects show what’s possible when innovation meets environmental responsibility. At D. Fritz Appraisals, we’re seeing firsthand how these sustainable choices are beginning to shape real estate values and influence appraisal considerations across Vancouver Island and beyond.

1. Sen̓áḵw Development – Vancouver

The Sen̓áḵw Development is one of the most ambitious Indigenous-led urban developments in Canadian history. Located on Squamish Nation land near downtown Vancouver, this transformative project will deliver over 6,000 rental homes across 11 towers—some reaching up to 56 storeys—with approximately 1,200 units designated as affordable housing.
Designed with a strong focus on sustainability, Sen̓áḵw aims to be Canada’s first large-scale, net-zero operational carbon housing development. The project emphasizes dense, transit-oriented living and will include a new transit hub, nearly 4,500 bicycle stalls, and limited vehicle parking to encourage low-carbon transportation choices.

Image credit: Revery Architecture/Westbank/Squamish First Nation

Beyond energy efficiency and climate resilience, Sen̓áḵw represents a groundbreaking model of Indigenous economic development and land stewardship—proving that urban growth can align with cultural values and sustainability goals.

2. Dockside Green – Victoria

Dockside Green is one of the most recognized sustainable communities in North America. Located along Victoria’s Inner Harbour, it integrates LEED Platinum buildings, on-site wastewater treatment, a district energy system, and green roofs.
This long-term development also influences how sustainability factors are used in real estate evaluation. At D. Fritz Appraisals, we consider features like energy efficiency and location sustainability when assessing property value and long-term viability in emerging green neighbourhoods.

Image Courtesy of www.docksidegreen.com

3. Vienna House – Vancouver

Vienna House is a collaboration between the City of Vancouver and BC Housing that sets a new bar for affordable, sustainable housing. Built to Passive House standards using mass timber construction, the project dramatically reduces energy use while providing durable, long-lasting homes.
This model is setting new expectations for energy performance in multi-unit housing, an important consideration for appraisers evaluating similar future developments.

Photo Courtesy of ViennaHouse.ca

4. Evolve UBC – University Endowment Lands

Part of UBC’s Campus as a Living Lab initiative, Evolve is a Passive House, net-zero-ready development that provides housing for faculty and staff. Designed to cut operational emissions and support occupant well-being, the project uses advanced monitoring to track performance.

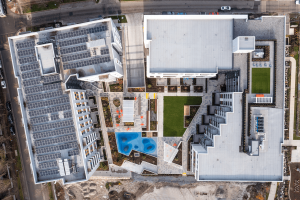
Image Courtesy of https://ubcproperties.com/project/evolve/

With increasing consumer and institutional demand for sustainable homes, developments like Evolve are shaping how the real estate industry, including real estate appraisers, understands the long-term market value of energy-efficient buildings.

5. Evergreen Terrace Redevelopment – Victoria

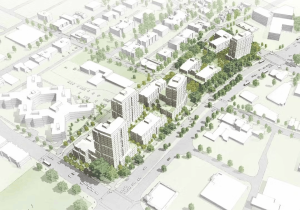
Victoria’s Evergreen Terrace Redevelopment (formerly BC Housing’s social housing site) is being reimagined as a mixed-income, sustainability-first community. It incorporates green design, increased density, and community-oriented planning.
As developments like this take shape, our appraisers work to capture the added value that sustainable design, improved livability, and walkability bring to urban residential spaces.

Image Courtesy of https://letstalkhousingbc.ca/victoria-evergreen-terrace

Making Smart Real Estate Decisions

At D. Fritz Appraisals, we understand that the real estate market is evolving, and sustainability is no longer just a bonus feature. Whether you’re buying, selling, or investing in a property, our expert appraisers take into account key factors like:

  • Energy efficiency and green certifications
  • Walkability and access to low-carbon transit
  • Sustainable building materials and design
  • Environmental resilience and long-term market appeal

By staying up to date on BC’s top sustainable developments, we help our clients make informed, future-focused real estate decisions across Vancouver Island and the Gulf Islands.

Frequently Asked Questions

What Makes British Columbia a Sustainability Leader?
BC’s leadership comes from its integration of green building policies, strong public support for climate action, and investment in long-term planning. Programs like CleanBC, the BC Energy Step Code, and municipal action plans make sustainability a cornerstone of development policy.

What Is the Most Innovative Sustainable Project in BC?
The Sen̓áḵw Development is among the most innovative—combining Indigenous leadership, clean energy, car-free living, and climate-smart design at a scale not seen elsewhere in Canada.

How Is Nature Integrated into BC’s Urban Planning?
Cities across BC are weaving nature into infrastructure through rain gardens, permeable pavements, green roofs, and urban forests. These features help manage water, cool cities, and create more livable communities.

Helping You Make the Right Investment

At D. Fritz Appraisals, we understand that buying, selling, or investing in real estate is one of life’s bigger decisions. That’s why we’re committed to providing you with the most accurate and reliable appraisal services across Victoria, lower Vancouver Island, and throughout the Gulf Islands.

As sustainability becomes a defining feature in the real estate market, having a clear understanding of how these innovations affect property values is more important than ever. Whether it’s a new net-zero home in a green neighbourhood or a commercial development prioritizing environmental performance, our team of certified appraisers brings over 40 years of local experience to help you assess real value—not just in the present but for the future.

If you’re looking to invest in Vancouver Island—home to some of the best places to live in BC—we’re here to support your decision-making with trusted insights and tailored evaluations. With our deep understanding of both traditional and evolving real estate factors, you can count on D. Fritz Appraisals to guide you confidently through BC’s dynamic property landscape.

Contact us today to get started—because smart decisions begin with the right appraisal.

We’re Hiring!
close slider

Job Title: AIC Candidate Appraiser

D. Fritz Appraisals Inc. is an established Real Estate Appraisal company that has been part of the Capital and Cowichan Valley community since 1998. We are excited to announce our company is ready to grow again and are searching for an AIC Candidate Appraiser to join our busy team to expand up-island in Nanaimo and the surrounding area.

The position available will be an independent contract, with a commission-based fee split. The successful Candidate will work under and be mentored by our AACI designated Appraiser. Our small team also consists of a CRA designated Appraiser (owner), three other AIC Candidates, and two Office Administrators. This is a work from home position, with an online virtual office to maintain and encourage communication and teamwork within the company. All computer software will be provided.

Responsibilities Include:

·      Perform on-site inspections, ensuring measurement accuracy, taking photographs and data collection;

·      Pull comparable sales and assign values to complete appraisal reports efficiently;

·      Meet turnaround times to ensure client satisfaction;

·      Develop relationships with lenders, brokers, clients, and other members of the public;

·      Continuously improve their knowledge regarding cost, market, and valuation trends;

·      Abide by all company policies and procedures­­­;

·      Attend staff meetings as required.

Qualifications Needed:

·      Valid Driver’s License and driving record that meets company standards

·      Clean Criminal Record check

·      A keen interest and knowledge of Vancouver Island’s real estate market

·      Registered Candidate Appraiser with the Appraisal Institute of Canada (AIC)

·      Must have proficient writing skills, be thorough and attentive to detail

Please forward a PDF copy of your resume and cover letter to [email protected].